Articles

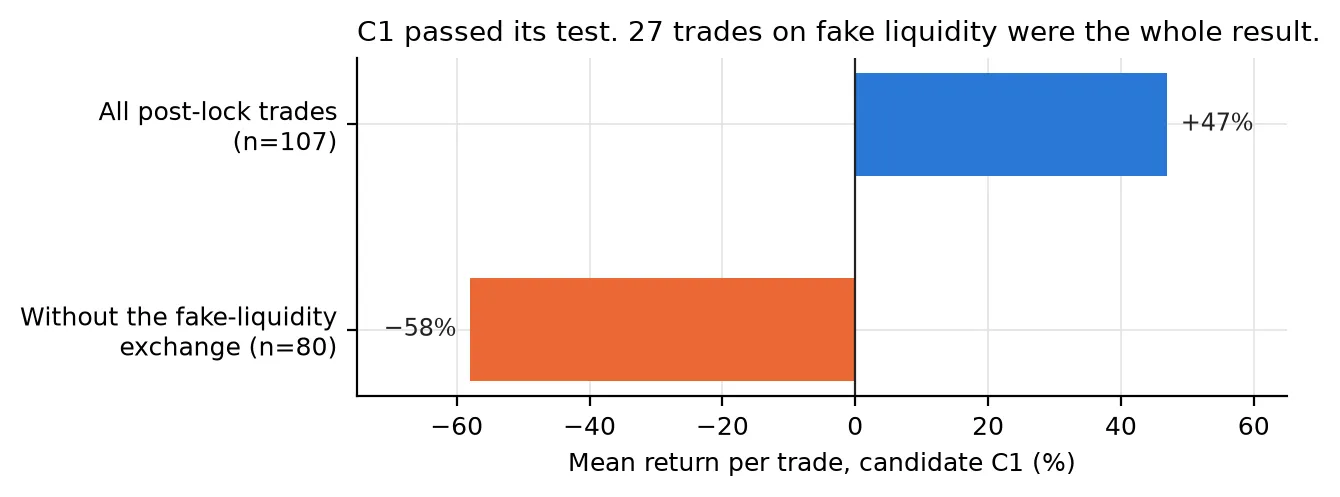
Building a memecoin trading bot: what the data said, and what real money said
Recording every new token forward, pre-registering every rule, and a real-money post-mortem that blamed the safety stops, not the strategy.
Quant, Research, Crypto, Python, Next.js
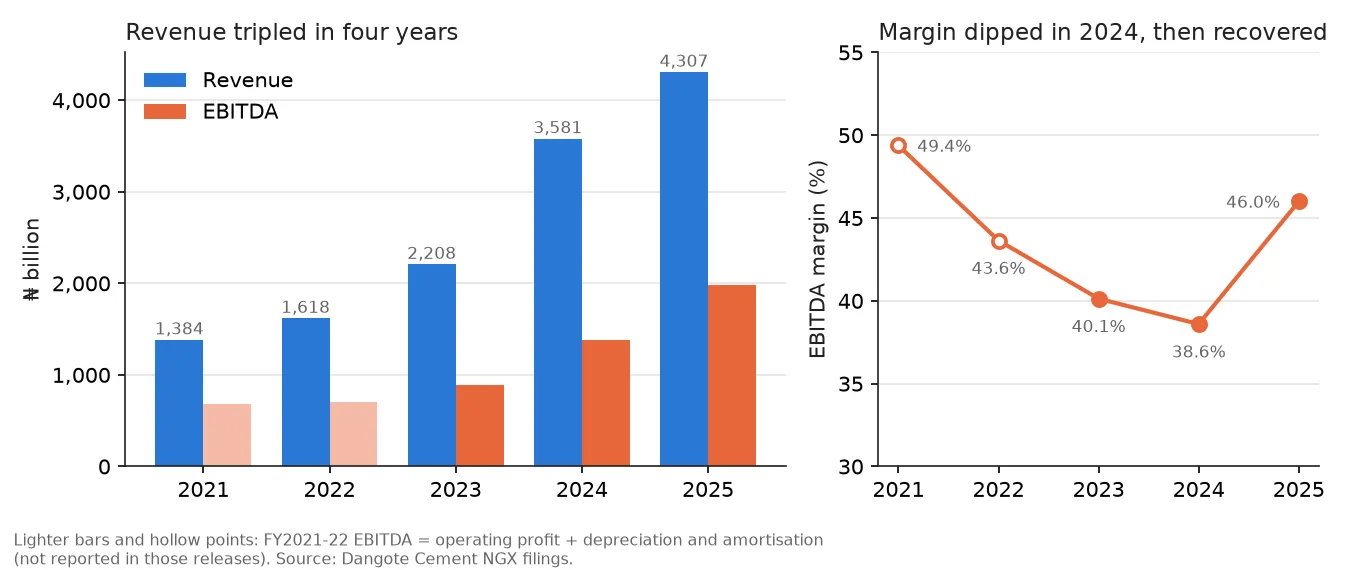
Dangote Cement is a better business than a year ago. Its share price assumes Nigerian rates will fall
An equity research note on Dangote Cement built from NGX filings: a DCF puts fair value at ₦871 against ₦1,490, a price that implies naira bond yields of 12.6%.
Equity research, Valuation, Nigeria, Python
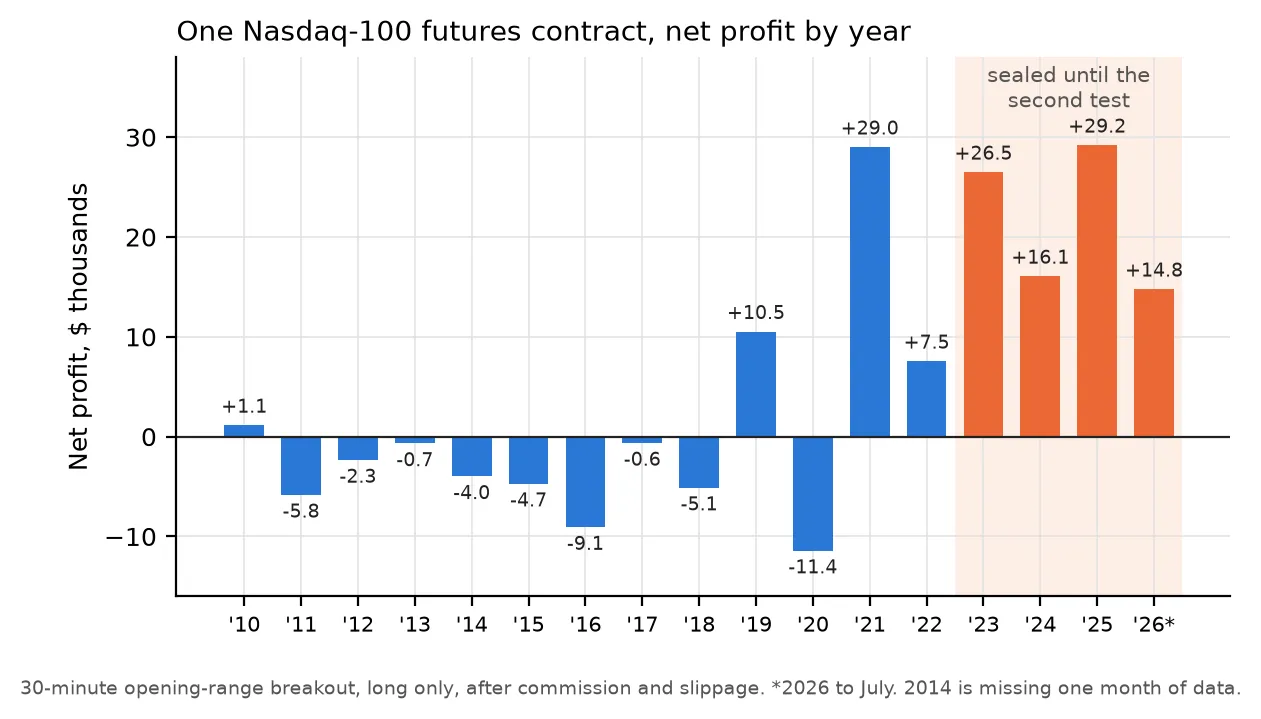
A day-trading strategy lost for nine years, then worked. Could you have known?
A YouTube Nasdaq breakout strategy lost money from 2010 to 2018, then made $86,510 on sealed 2023–26 data. Neither regime filter would have told you when.
Quant, Research, Backtesting, Trading
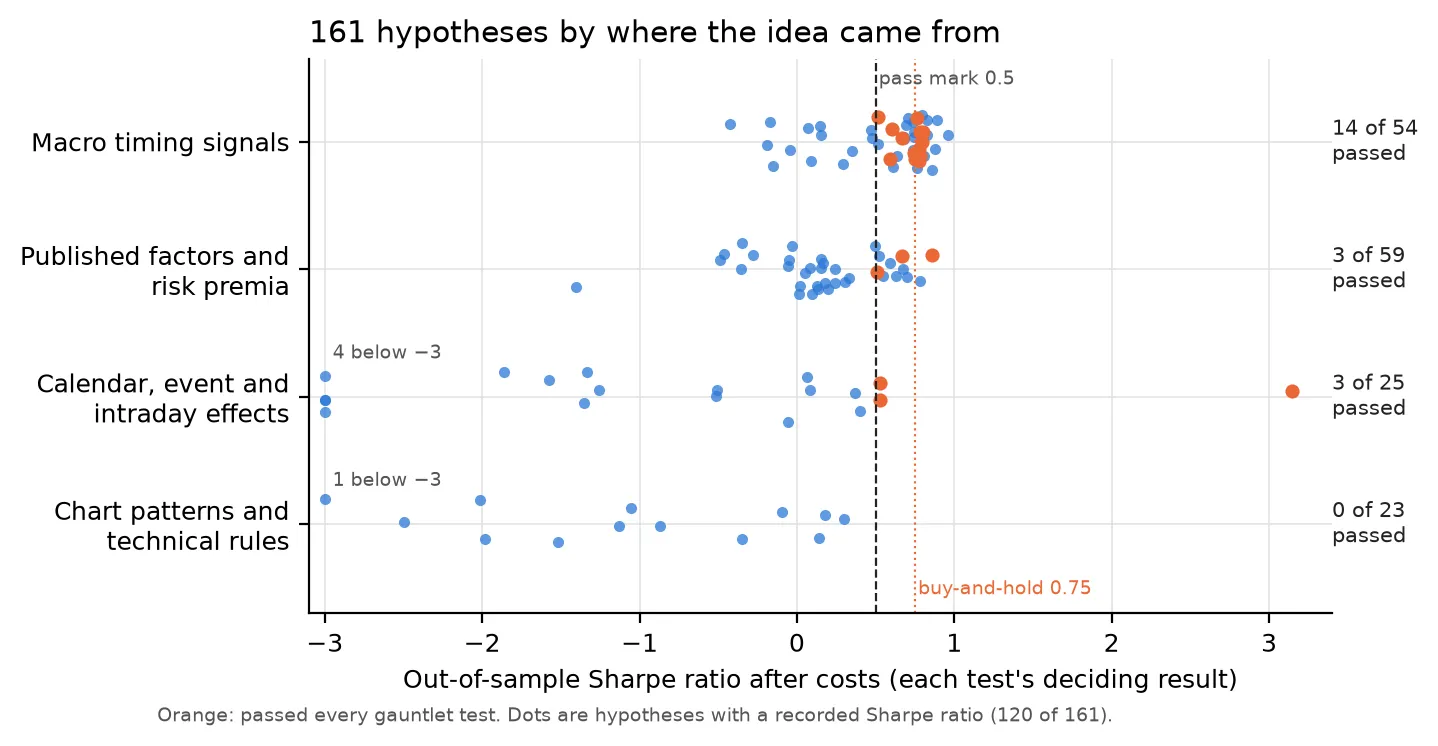
161 trading hypotheses: what survived, and where my tests were wrong
A scoreboard of 161 pre-registered trading ideas, from chart patterns to risk premia. Lore never came close; textbook premia barely did better.
Quant, Research, Backtesting, Trading
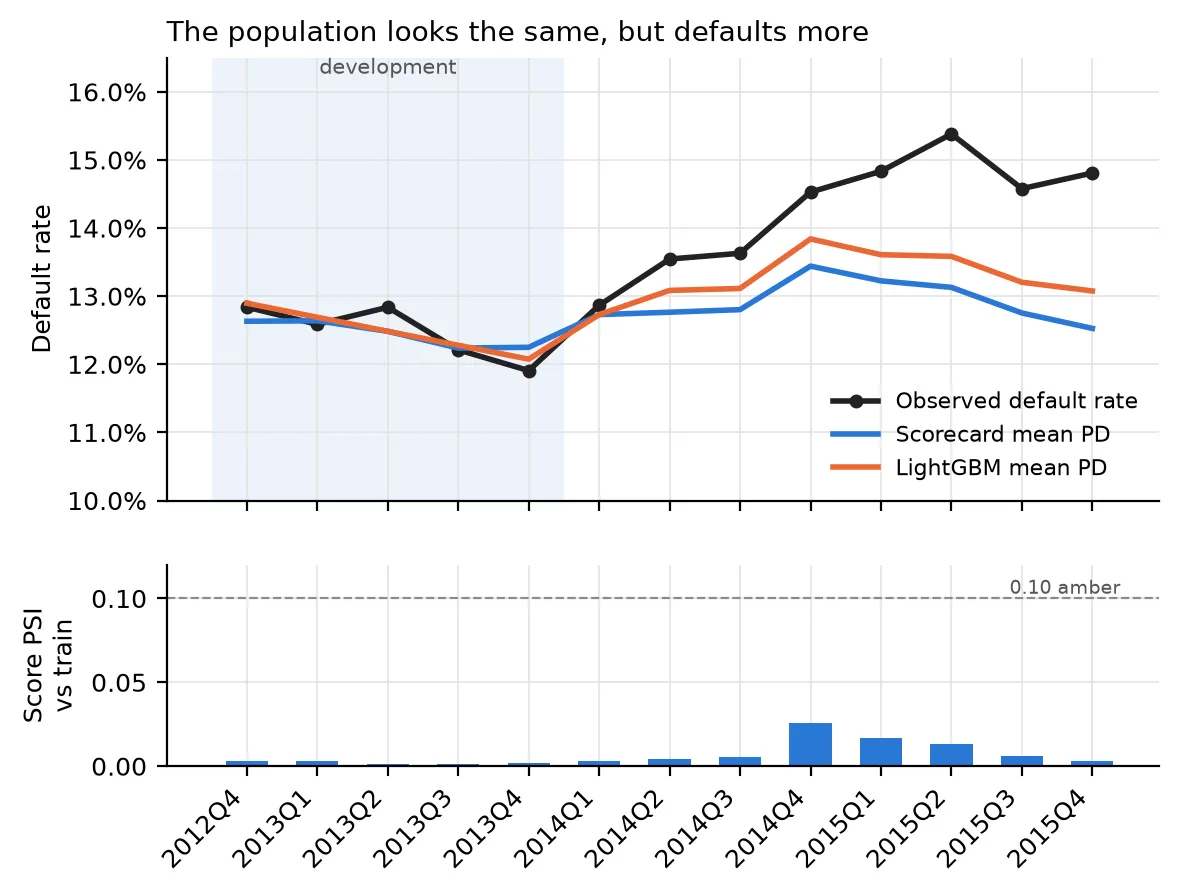
I built a bank-style credit model. The health check said it was fine while losses rose
I built a credit scorecard and a LightGBM PD model on 620,783 Lending Club loans and validated them like a bank: ranking held, but PSI missed the drift.
Credit risk, Python, Machine learning, Data
Costs killed my day trading on stocks. On the indices, the pattern flipped
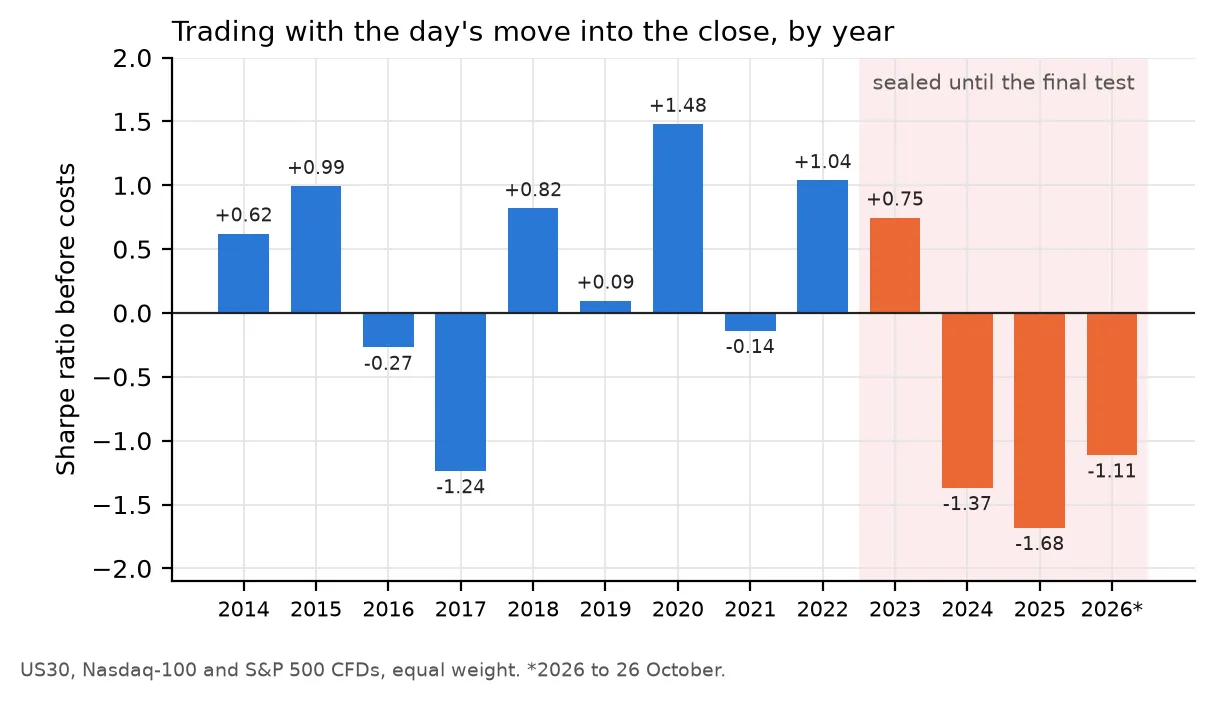
Day trading on stocks lost to costs, so I tested the best-known intraday pattern on stock indices at futures costs. It worked for a decade, then reversed.
Quant, Research, Backtesting, Trading
My market-timing signals passed every test. Buy-and-hold nearly did too
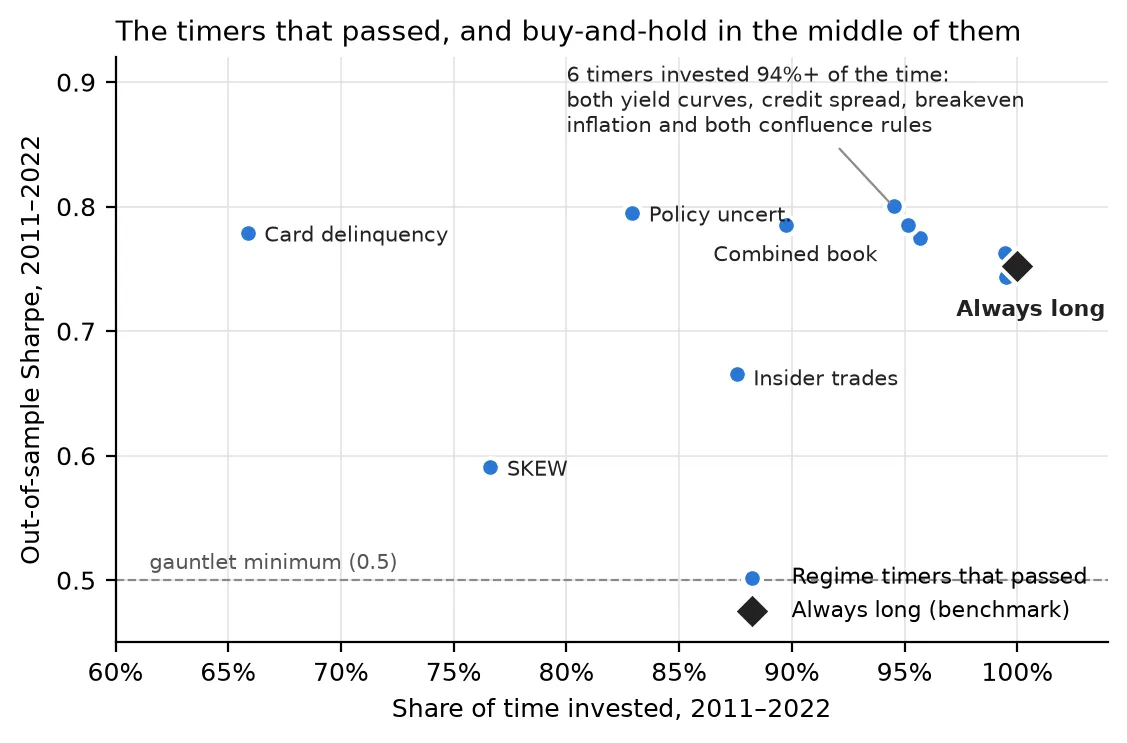
Ten macro regime timers passed my backtest gauntlet; buy-and-hold failed only on a technicality. Out of sample, all ten made less than staying invested.
Quant, Research, Backtesting, Python
I backtested Smart Money Concepts properly. Six rules, no edge
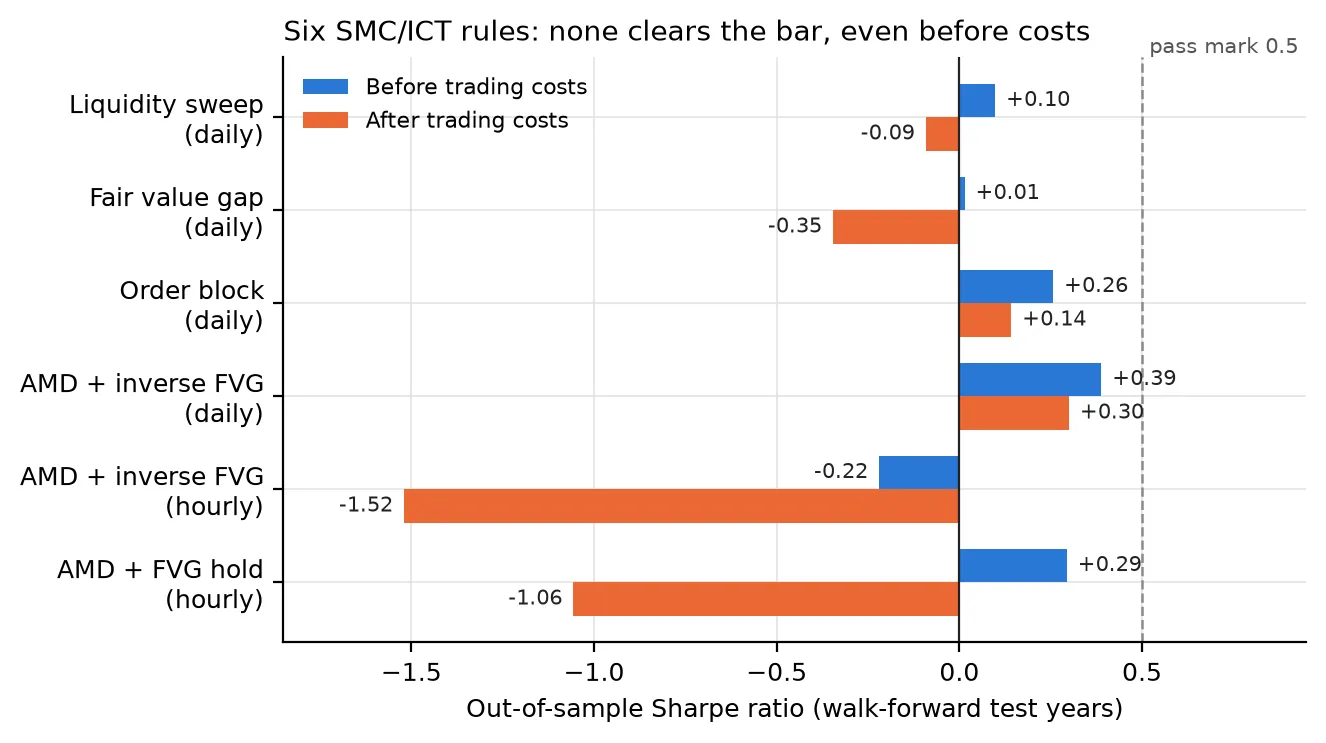
I coded six Smart Money Concepts (ICT) rules, from liquidity sweeps to order blocks, and backtested them on FX and gold back to 2005. None passed.
Quant, Research, Backtesting, Trading
Fifty-six trading hypotheses: what systematic signal research actually looks like
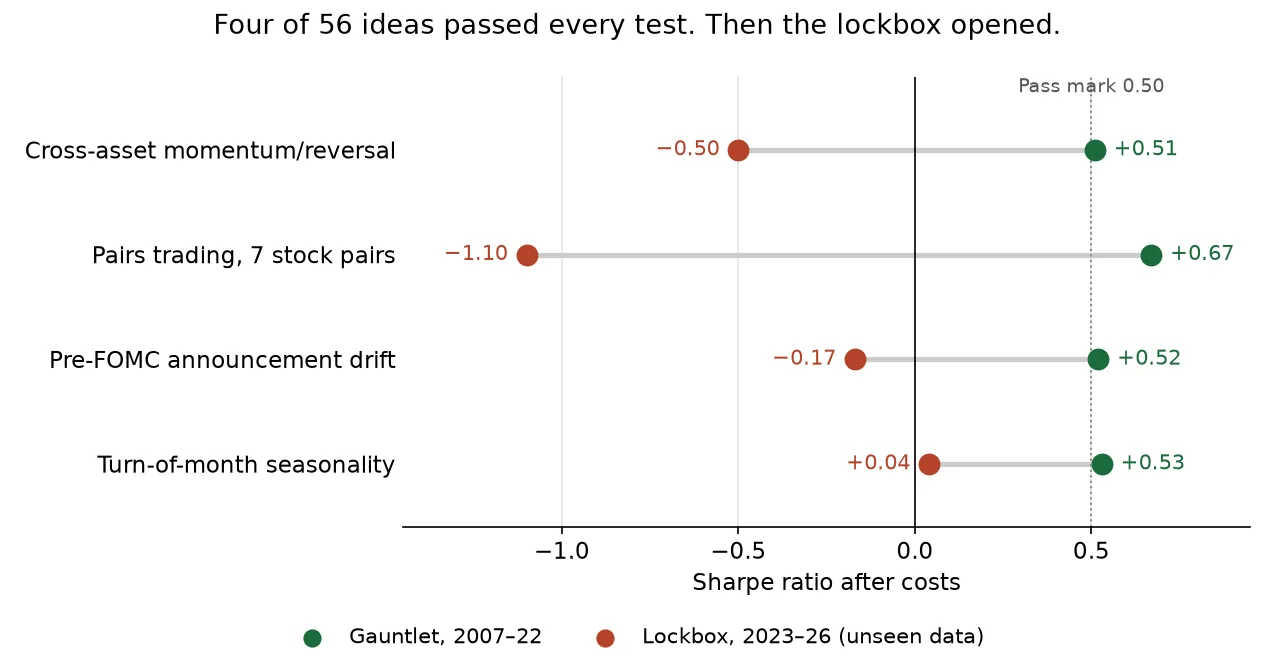
A pre-registered five-gate backtest gauntlet, a one-shot holdout, and why passing every test still wasn't enough.
Quant, Research, Backtesting, Python
Building a naira yield curve from public data, and what it says about MPC decisions
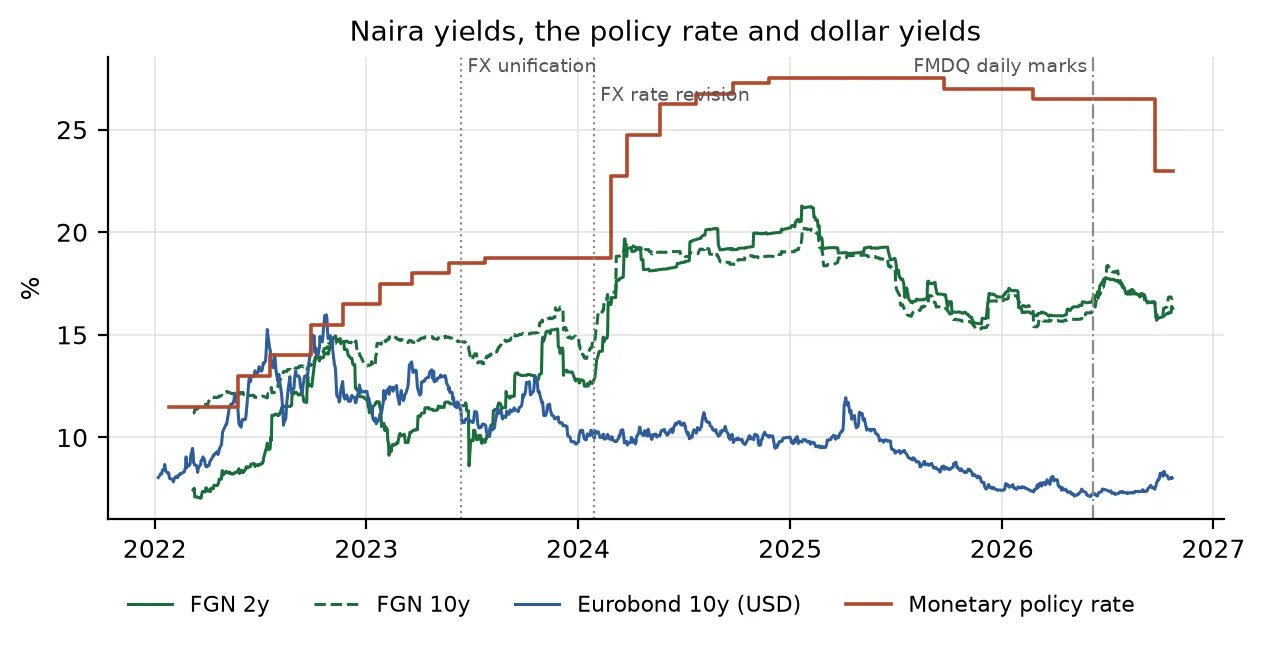
Naira and Eurobond yield curves built from FMDQ, DMO and CBN data. FGN bond yields now move before MPC rate decisions; in 2010–17, in the decision week.
Fixed income, Python, Nigeria, Data